

How Predictability Creates Financial Peace: Build Simple Systems That Replace Money Stress With Stability
Financial peace is often treated like a reward reserved for people who earn a large income.
The assumption is simple: If you make enough money, you will finally stop worrying about it.
But income alone does not guarantee peace.
Someone can earn a strong salary and still feel anxious every time a bill arrives.
Another person can earn less but feel steady because they understand exactly what is coming in, what must go out, and what their money needs to accomplish.
The difference is often predictability.
Financial predictability means you are not constantly being surprised by your own financial life.
You know when your income arrives.
You understand your regular expenses.
You have a plan for irregular costs.
You know how much you can spend, save, and direct toward your goals.
That knowledge creates stability.
You may not control every financial event, but you can create enough structure to stop living in permanent uncertainty.
Financial Peace Is More Than Having More Money
More income can improve your financial situation.
It can give you additional room to save, invest, pay down debt, and handle rising costs.
But more money does not automatically create better habits.
Without a clear system, additional income can disappear into higher spending, forgotten subscriptions, unplanned purchases, and loosely defined goals.
The numbers get bigger, but the confusion remains.
Financial peace is not simply the absence of financial problems.
It is the presence of financial clarity.
You feel more grounded when you can answer basic questions such as:
How much money normally comes in each month?
When are my major bills due?
What amount is available after essential expenses?
What am I currently saving toward?
Which financial priority comes first?
What will I do when an irregular expense appears?
You do not need perfect answers down to the penny.
You need reliable answers that are clear enough to guide your decisions.
That is how predictability begins turning financial tension into practical control.
💡 Create More Clarity Around Your Money
A simple financial structure can help you make calmer decisions without tracking every dollar perfectly.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Why Financial Uncertainty Feels So Exhausting
Financial uncertainty creates more than a numbers problem.
It creates a mental burden.
When you do not know whether there will be enough money for the next bill, your mind remains alert.
You may repeatedly check your account, delay opening statements, or mentally calculate the same expenses throughout the day.
Even when nothing is immediately wrong, uncertainty makes it difficult to relax.
Your mind keeps returning to unanswered questions:
Did that payment already come out?
Can I afford this purchase?
What happens if the car needs a repair?
Am I forgetting a bill?
How much can I safely move into savings?
This continuous monitoring consumes attention
It can also lead to reactive choices.
You may pay whatever feels most urgent, move money between accounts without a plan, use credit to solve short-term gaps, or avoid reviewing your finances because the uncertainty feels overwhelming.
Predictability interrupts this cycle.
Once your financial obligations are recorded and your priorities are defined, your brain no longer has to hold every detail at once.
Your system becomes the place where those decisions live.
The Four Areas That Create Financial Predictability
Financial predictability does not require an advanced spreadsheet or a complicated budgeting system.
It begins by creating structure in four areas: income, bills, savings, and priorities.
1. Predictable Income Awareness
Your income does not have to be identical every month for you to understand it.
If you receive a regular paycheck, record the amount and expected deposit dates.
If your income varies, review the previous three to six months and identify a reasonable monthly baseline.
Use the lower end of your normal income range when planning essential expenses.
This protects you from building a spending plan around your best month.
For example, if your recent monthly income ranged from $3,200 to $4,100, you might build your core plan around $3,200.
Any income above that amount can then be assigned intentionally.
It could support:
Emergency savings
Debt reduction
Upcoming annual expenses
Investments
Business development
Necessary home or vehicle maintenance
This creates a dependable foundation without pretending that variable income is completely predictable.
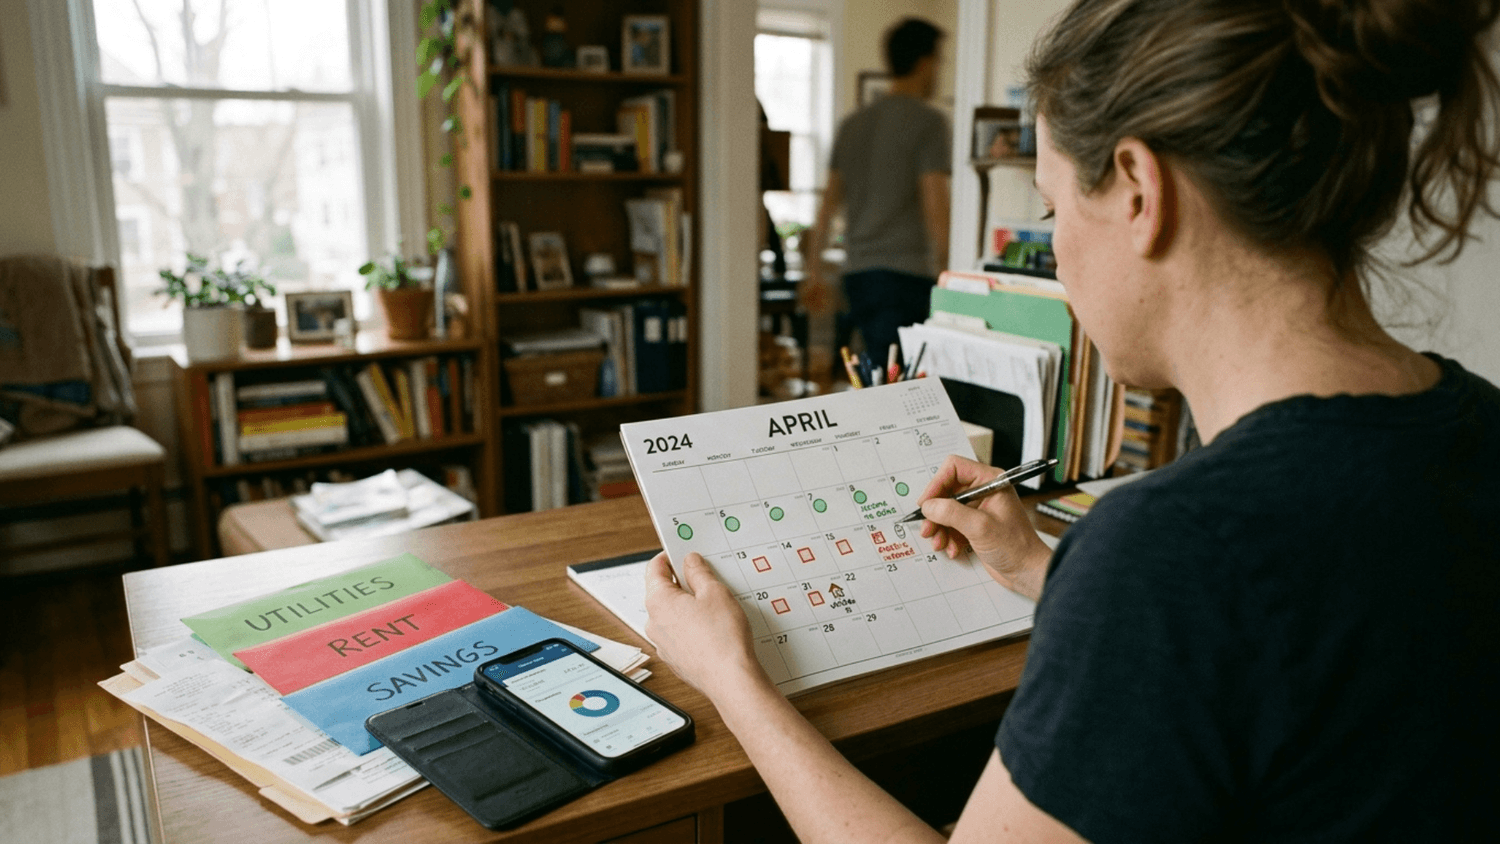
2. Predictable Bill Tracking
A bill is more stressful when it feels like a surprise.
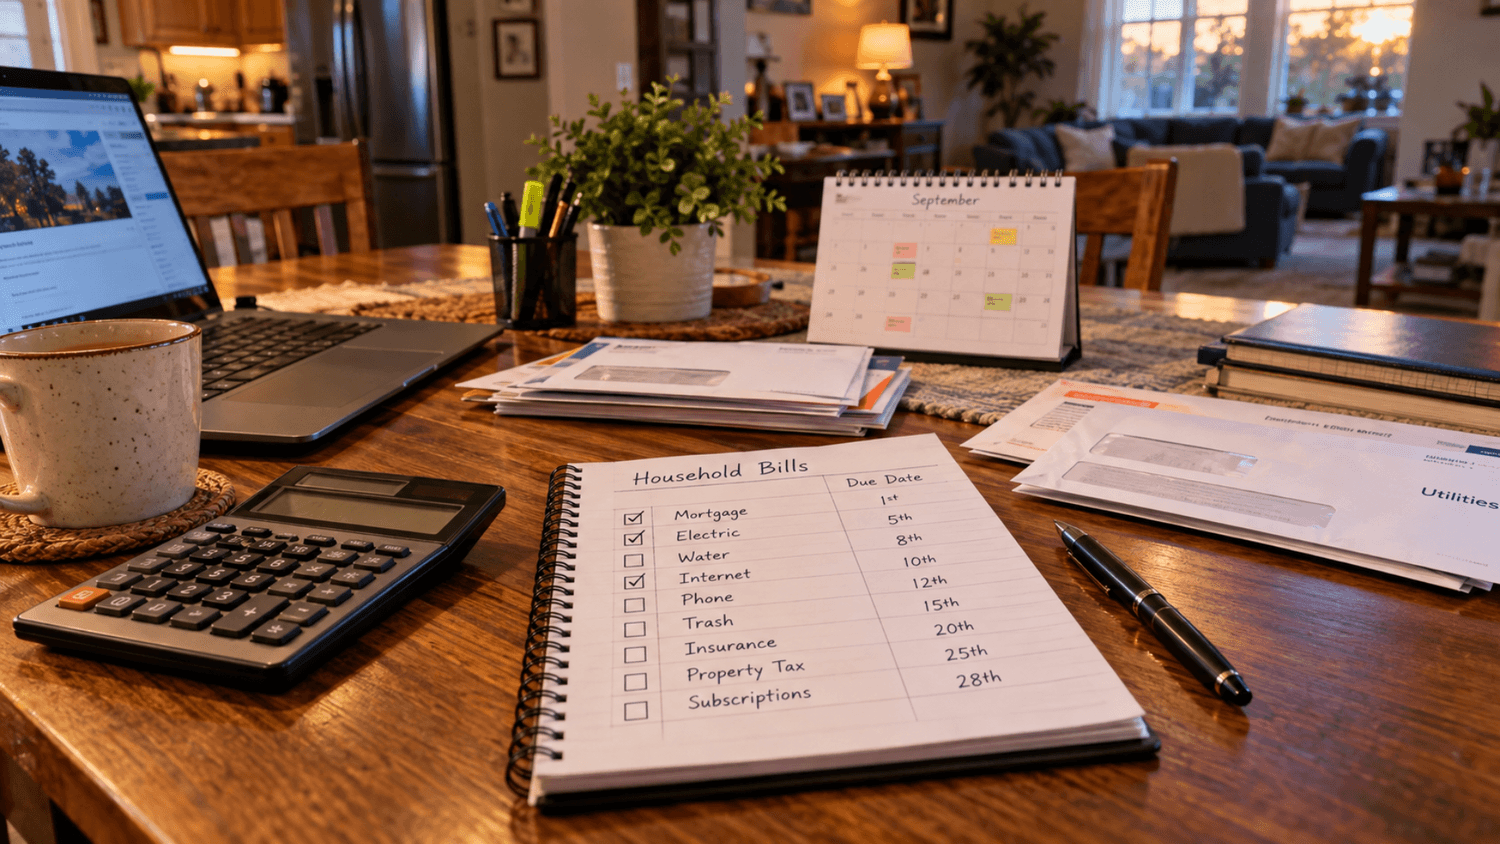
Create one complete list containing each recurring obligation, its expected amount, and its due date.
Include monthly bills as well as expenses that appear quarterly, semiannually, or annually.
Your list may include:
Housing
Utilities
Insurance
Phone and internet
Transportation
Minimum debt payments
Memberships and subscriptions
Property-related expenses
Business services
Annual renewals
Once these costs are visible, you can prepare for them instead of reacting when they arrive.
💡 Turn Monthly Obligations Into a Clear Plan
Knowing what is due and when it is due gives you a stronger foundation for saving, spending, and planning ahead.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
3. Predictable Savings
Saving what remains at the end of the month often produces inconsistent results.
There may be no money left because every unassigned dollar gradually finds another use.
Automatic transfers make saving more predictable.
A transfer scheduled shortly after income arrives treats saving like a planned financial obligation instead of an optional decision.
The amount does not need to be large.
A dependable $20, $50, or $100 transfer can be more useful than waiting for the perfect month to save several hundred dollars.
Regular transfers create evidence that your financial system is working.
You can automate money toward:
An emergency fund
A home or vehicle repair fund
Annual insurance premiums
Holiday expenses
Retirement
A business reserve
A future purchase
The goal is not to automate more than you can afford.
The goal is to choose a realistic amount that can continue without creating new financial pressure.
4. Predictable Priorities
Money becomes difficult to manage when everything feels equally important.
You may want to build savings, pay off debt, invest, replace an appliance, improve your home, and grow a business at the same time.
All of these goals may be reasonable, but trying to fund them equally can weaken your progress.
Define what comes first.
A basic order might be:
1. Cover essential expenses.
2. Maintain a small cash buffer.
3. Make required debt payments.
4. Prepare for known upcoming costs.
5. Build emergency savings.
6. Increase debt payments or long-term investments.
Your order can change based on your circumstances.
What matters is that the order is intentional.
Clear priorities prevent every new desire or inconvenience from rewriting your financial plan.
Build a Spending Plan You Can Actually Use
A spending plan tells your money where it needs to go before daily decisions begin competing for it.
Start with the income amount you can reasonably expect.
Then subtract essential commitments such as housing, food, transportation, utilities, insurance, and minimum debt payments.
After that, assign money to savings, irregular expenses, flexible spending, and personal priorities.
The plan should reflect your real life.
If you regularly spend money on household items, transportation, medication, family needs, or business tools, include those categories.
Do not create an idealized plan that only works if nothing unexpected happens and you never enjoy your money.
A usable plan leaves some room for flexibility.
It also gives you a clear stopping point.
When a category has been used, you know that additional spending will require a deliberate adjustment elsewhere.
Create a Financial Buffer Between You and Stress
Predictability becomes stronger when your plan includes a buffer.
A buffer is money that remains available for small changes in cost or timing.
It protects your account when a utility bill is slightly higher, a deposit arrives later than expected, or an everyday expense costs more than planned.
This is different from a full emergency fund.
An emergency fund is designed for significant unexpected events.
A checking-account buffer handles ordinary variation.
Your starting buffer might be $100, $250, or one week of essential expenses.
Choose an amount that fits your current situation and build it gradually.
Once established, avoid treating the buffer as available spending money.
Its purpose is to keep normal fluctuations from creating unnecessary financial emergencies.
💡 Give Your Financial Plan Room to Breathe
A small buffer can prevent ordinary changes from disrupting your bills, savings, and longer-term goals.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
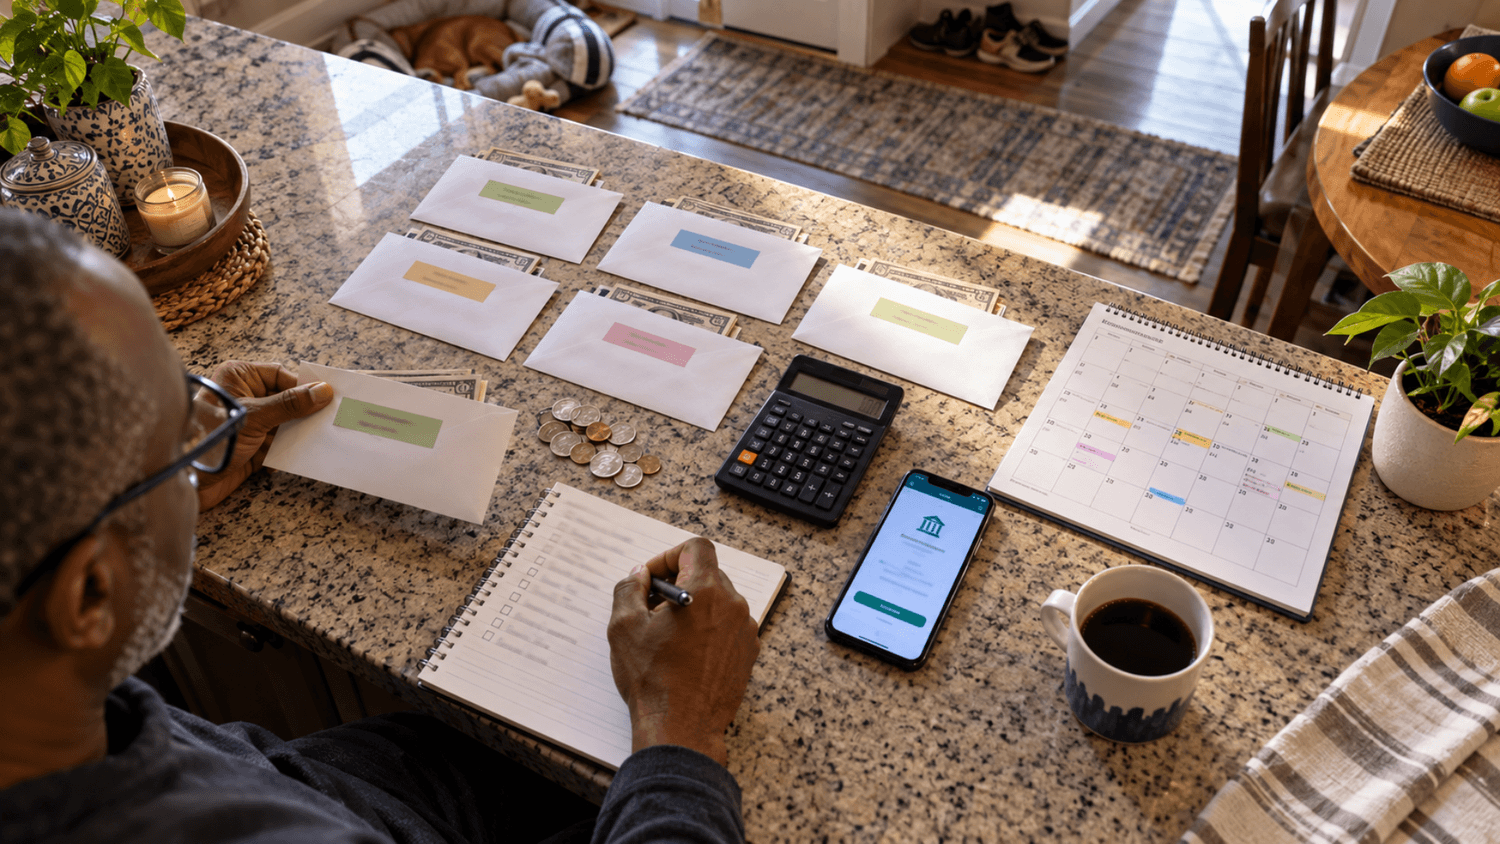
Plan for Expenses That Are Predictable but Not Monthly
Many financial surprises are not truly unexpected.
Vehicle registration, annual subscriptions, insurance premiums, holiday spending, routine maintenance, and school expenses often occur on a predictable schedule.
The problem is that they do not appear every month, so they are easy to ignore until they become urgent.
Create a list of these irregular expenses and estimate their yearly cost.
Then divide each amount by 12.
If an annual expense is approximately $600, setting aside $50 per month turns one large payment into a manageable monthly commitment.
These small reserves are sometimes called sinking funds.
The name matters less than the purpose: preparing gradually for an expense you know will eventually arrive.
Use Automation Without Losing Awareness
Automation reduces the number of financial decisions you must remember.
You can automate recurring bills, savings transfers, retirement contributions, and regular debt payments.
This improves consistency and lowers the risk of missing important dates.
However, automation should support awareness, not replace it.
Continue reviewing your accounts regularly.
Confirm that deposits arrived, automatic payments were processed correctly, and your balance can support upcoming transactions.
A simple routine may include:
A five-minute account review twice a week
A bill calendar check before each payday
A monthly review of spending categories
A quarterly review of subscriptions and recurring charges
A yearly update of savings targets and major expenses
These brief reviews keep your financial system accurate without allowing money management to consume your entire day.
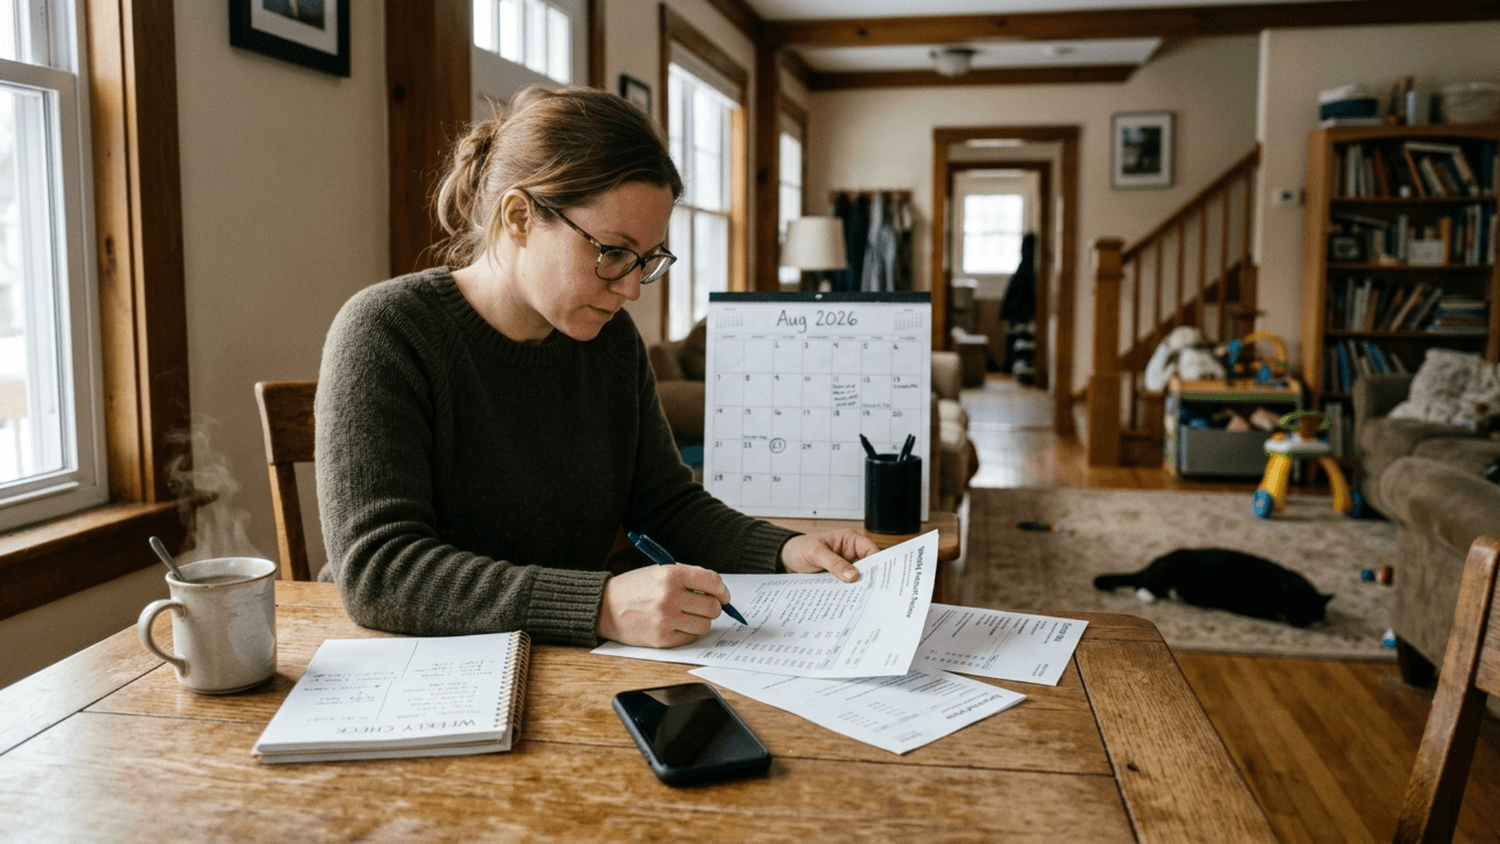
Practice a Weekly Financial Reset
A short weekly reset can prevent small issues from becoming larger problems.
Choose one consistent day and review your current balances, upcoming bills, recent purchases, and planned transfers.
Ask four questions:
1. What came in this week?
2. What went out?
3. What is due before the next review?
4. Does anything need to be adjusted?
This process might take 10 to 20 minutes.
The value comes from repetition.
Regular contact with your finances makes the information familiar.
Familiarity reduces avoidance, and reduced avoidance improves decision-making.
What to Do When Your Income Is Irregular
Predictability is still possible when income changes from month to month.
The system simply needs different rules.
First, identify your lowest dependable monthly income.
Build essential spending around that number whenever possible.
Second, separate business or freelance income from personal spending.
Transfer a planned amount to yourself instead of spending directly from incoming payments.
Third, create a holding account for higher-income months.
Extra income can remain there to support months when earnings are lower.
Fourth, assign percentages when fixed amounts are difficult.
For example, each payment might be divided among taxes, operating expenses, personal income, savings, and future goals.
You may not know exactly how much will arrive, but you can decide what happens to the money when it does.
That is another form of predictability.
Make Your Financial System Easier to Maintain
A financial system should reduce confusion, not create another demanding project.
Use tools you will continue using. That may be a notebook, calendar, spreadsheet, banking feature, or budgeting app.
Keep the system simple enough to answer three questions quickly:
What money is available now?
What obligations are coming next?
What financial goal currently has priority?
If your system requires hours of detailed tracking before you understand your situation, simplify it.
You can group small purchases into broader categories.
You can schedule recurring reviews instead of checking constantly.
You can keep one central bill list instead of scattering reminders across several places.
The best system is not the most impressive one.
It is the one you can trust and maintain.
Stability Creates Space for Growth
Financial stability is not the end of wealth building.
It is the foundation.
When your bills are organized, savings are consistent, and priorities are clear, you can make longer-term decisions with greater confidence.
You can evaluate investments without risking money needed for next month’s rent.
You can plan a business expense without guessing whether a major bill has been forgotten.
You can pursue growth without allowing every setback to become a crisis.
Predictability does not eliminate risk.
It helps you take risk from a more stable position.
That distinction matters.
Wealth is not only about increasing the value of what you own.
It is also about strengthening your ability to handle obligations, absorb disruption, and make decisions without constant financial panic.
💡 Build Stability Before Chasing Bigger Numbers
Clear systems help you protect what you have while creating room for thoughtful, long-term financial growth.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Final Thought
Financial peace does not require knowing exactly what will happen in every part of your life.
It comes from knowing how your money is organized and what you will do next.
A clear spending plan tells you what your income must cover.
A bill schedule prevents avoidable surprises.
Automatic transfers make saving consistent.
Defined priorities keep competing goals from pulling your money in every direction.
Start with one area.
List your bills.
Schedule a small savings transfer.
Create a weekly review.
Choose the financial priority that matters most right now.
Then repeat the process until it becomes familiar.
Predictability turns money management from a constant source of uncertainty into a dependable system.
That system creates stability, and stability gives you the mental space to plan, adapt, and build.
You do not need millions of dollars to begin experiencing financial peace.
You need greater clarity about what is coming in, what is going out, and what your money needs to do next.

Categories


Trending
Curious about Java Burn? Discover how this fat-burning coffee additive works, what ingredients it uses, and if it’s right for your daily routine.
Looking for real ways to make extra money in 2024? Here are 15 legitimate side hustles and online income ideas that actually work — no scams, no fluff.
Discover how to build real confidence using small, science-backed micro-habits. No fluff — just proven strategies that actually work.

About me

Hi there 👋 My name is Lisa Grove, I'm the maker of This Blog. One of my favorite things is travel, fun and sun :)
💡 Keep Exploring: Handpicked Reads for You
Discover proven strategies to attract leads using Facebook & Instagram — no ad budget needed.
Learn how to write subject lines and content that get clicks, opens, and responses.

Start your journey toward financial freedom with this simple, proven framework.
📬 Want Smart Marketing Tips in Your Inbox?
Join our free newsletter for weekly tips that help you grow faster and smarter.
© 2025 reebesthelp.com. All rights reserved.