

Why People Avoid Simple Wealth Systems: The Real Power of Doing the Financial Basics Consistently
Wealth Building Is Usually Less Complicated Than It Looks
People often assume that building wealth requires advanced investing knowledge, a complicated business strategy, or access to information that ordinary people do not have.
That belief makes wealth feel distant.
It also creates a convenient reason to wait.
If the process is too complicated, you can tell yourself that you need another book, course, spreadsheet, expert, or perfect opportunity before you begin.
The truth is less dramatic.
Most practical wealth systems are built around a few basic actions:
Track what you earn.
Know what you spend.
Keep some of the difference.
Protect yourself from expensive emergencies.
Use part of your money to build assets.
Repeat the process for years.
These steps are not exciting, but they are powerful.
They create visibility, control, and forward movement.
The difficulty is not understanding the system.
The difficulty is following it when nobody is watching, progress feels slow, and easier choices are available.
Simple systems remove the mystery.
Once the mystery disappears, responsibility becomes harder to avoid.
Simplicity Removes Financial Excuses
Complexity gives people places to hide.
Someone can spend months comparing budgeting apps without tracking a single full month of expenses.
Another person can study investments constantly while never creating room in the budget to invest.
Research can be useful, but it can also become a substitute for action.
A simple system forces clear questions:
How much money came in?
Where did it go?
How much did you keep?
What debt became smaller?
What asset became larger?
What needs to change next month?
Those questions leave little room for guessing.
They connect daily financial behavior to actual results.
If the numbers reveal that convenience spending is consuming money meant for savings, the issue is no longer hidden.
If income is too low to support current expenses and future goals, that becomes visible too.
This clarity can feel uncomfortable, but it is useful.
You cannot improve a pattern that you refuse to see.
💡 Ready to Build Real Confidence (Without Overthinking It)?
If you’re tired of starting over and want a simple system that actually sticks, this is for you.
👉 Start building confidence today:
Start small. Stay consistent. Watch what happens.
Why Consistency Feels Harder Than Complexity
A complicated strategy can feel impressive.
A consistent strategy often feels repetitive.
That is one reason people abandon simple financial systems.
They expect wealth building to feel like a series of major breakthroughs, but much of it looks ordinary:
Reviewing transactions every week
Paying bills on time
Avoiding unnecessary fees
Contributing to savings regularly
Investing according to a plan
Saying no to purchases that delay larger goals
None of these actions creates instant transformation.
Their strength comes from accumulation.
Saving $25 once will not change your financial life.
Saving it repeatedly establishes a habit and creates a starting reserve.
Increasing that amount as your finances improve turns a small routine into meaningful capital.
The same principle applies to investing, debt reduction, and business ownership.
Small actions gain strength when they continue.
People often underestimate repetition because each individual action looks insignificant.
They notice the amount invested today but fail to picture years of contributions, potential growth, and increased financial discipline.
Wealth is rarely created by one perfect move.
It is usually built through a series of reasonable moves that support one another.
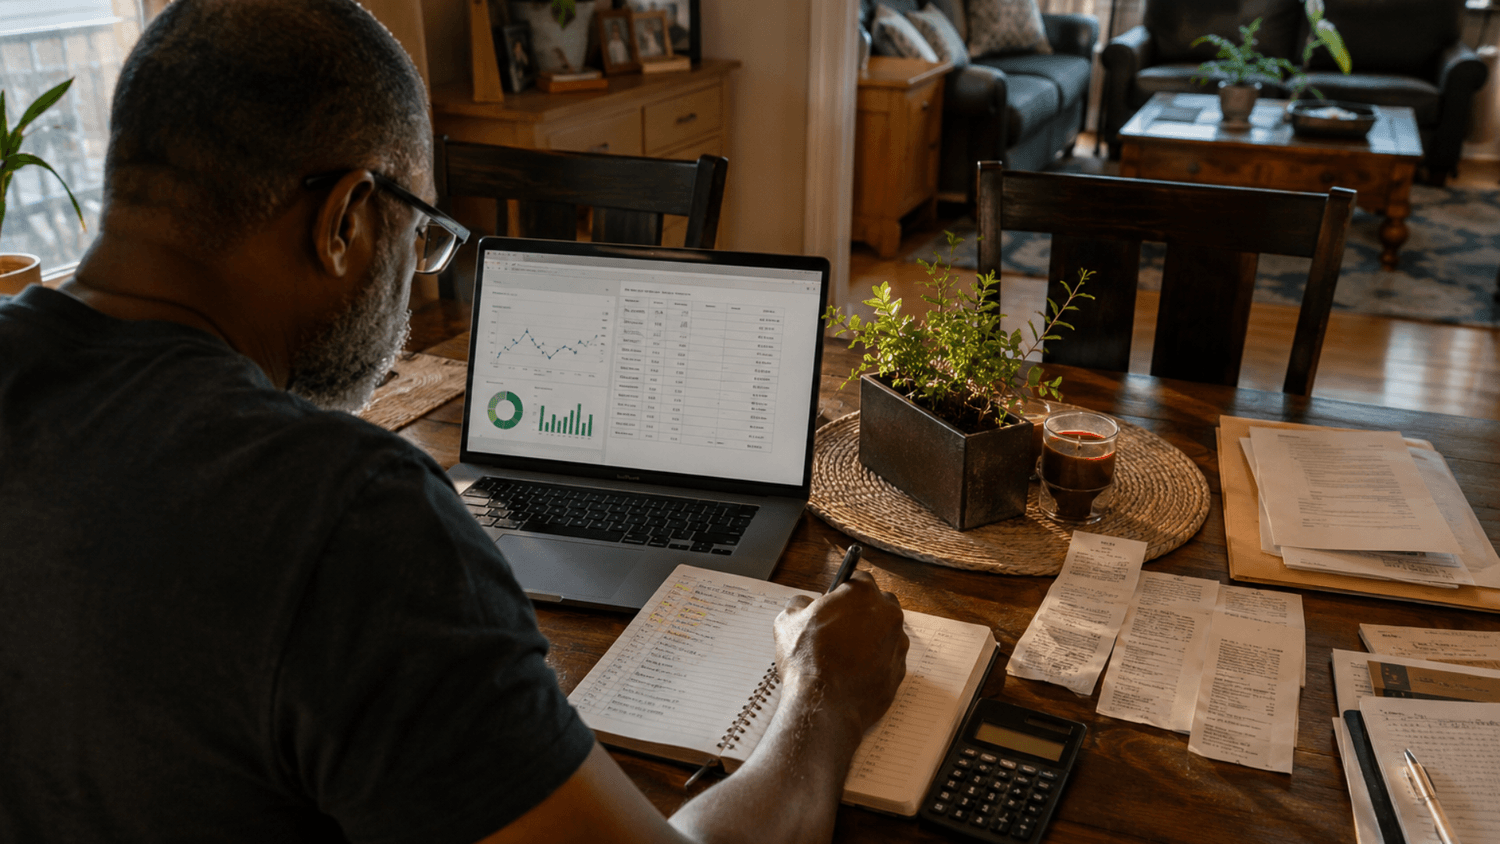
The Four-Part Simple Wealth System
A useful wealth system does not need dozens of categories.
It needs enough structure to show you what is happening and guide your next action.
1. Track Income
Begin with your actual take-home income, not your salary before deductions.
Include every dependable source:
Employment income
Business income
Rental income
Freelance payments
Benefits or pensions
Other recurring income
If your income changes each month, use a conservative baseline based on recent history.
Build essential spending around the lower, more dependable amount instead of your best month.
Tracking income helps you avoid planning with money that may never arrive.
2. Control Spending
Controlling spending does not mean removing every enjoyable part of life.
It means deciding which expenses deserve space in your financial plan.
Start with the largest categories because they have the greatest effect:
Housing
Transportation
Food
Insurance
Debt payments
Subscriptions
Recurring household expenses
A few small purchases can add up, but reducing one large recurring expense may create more progress than cutting every minor comfort.
Control begins when spending becomes intentional instead of automatic.
3. Build Assets
An asset is something that can store value, grow in value, or produce income.
Examples may include retirement investments, diversified investment accounts, a properly managed business, or income-producing property.
The right choice depends on your finances, goals, time horizon, and tolerance for risk.
The larger principle is universal: some portion of current income should support future financial strength.
Asset building turns earned income into ownership.
4. Repeat
Repetition is what transforms the first three steps into a wealth system.
Review the plan, correct mistakes, increase contributions when possible, and continue.
A system should survive imperfect months without being abandoned.
💡 Build a Financial Foundation You Can Repeat
You do not need a complicated strategy to start. You need a clear process that works with your real income and responsibilities.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Ownership Begins With Facing the Numbers
Financial ownership is not the same as blaming yourself for everything that has happened.
Unexpected medical costs, job losses, inflation, family responsibilities, and emergencies can place real pressure on a household.
A simple wealth system does not pretend that every obstacle is within your control.
Ownership means identifying the choices that remain available.
You may not control the price of groceries, but you can review how food spending fits into the larger plan.
You may not control an unexpected repair, but you can begin rebuilding the reserve after using it.
You may not be able to increase your income immediately, but you can identify the skills, opportunities, or business actions that could improve it over time.
This approach replaces helplessness with direction.
Facing the numbers also separates facts from financial anxiety.
A person may feel that everything is out of control, but a written review might reveal two specific problems: an expensive debt payment and irregular overspending in one category.
That is still serious, but it is no longer vague.
A defined problem can become a plan.
Why Starting Over Keeps People Stuck
Many people create a new budget whenever motivation is high.
They follow it briefly, overspend, and decide the entire plan has failed.
Then they wait for another fresh start.
This all-or-nothing cycle creates more damage than an imperfect month.
A useful system should include correction instead of requiring perfection.
If you overspend in one category, review why it happened.
Was the amount unrealistic?
Did an unusual event occur?
Did convenience spending increase because your schedule became difficult?
Adjust the next decision instead of destroying the whole structure.
Wealth systems work more like steering than following a perfectly straight road.
Small corrections keep you moving in the intended direction.
A missed savings contribution does not erase previous progress.
Resume when the next income arrives.
A temporary emergency expense does not make the emergency fund pointless.
Using the reserve for a real emergency proves why the reserve matters.
The goal is not to avoid every disruption.
It is to build a system that helps you recover.
Automate the Right Parts
Automation reduces the number of decisions required to maintain progress.
You may be able to automate:
Transfers to emergency savings
Retirement contributions
Investment deposits
Essential bill payments
Additional debt payments
Transfers into business or tax accounts
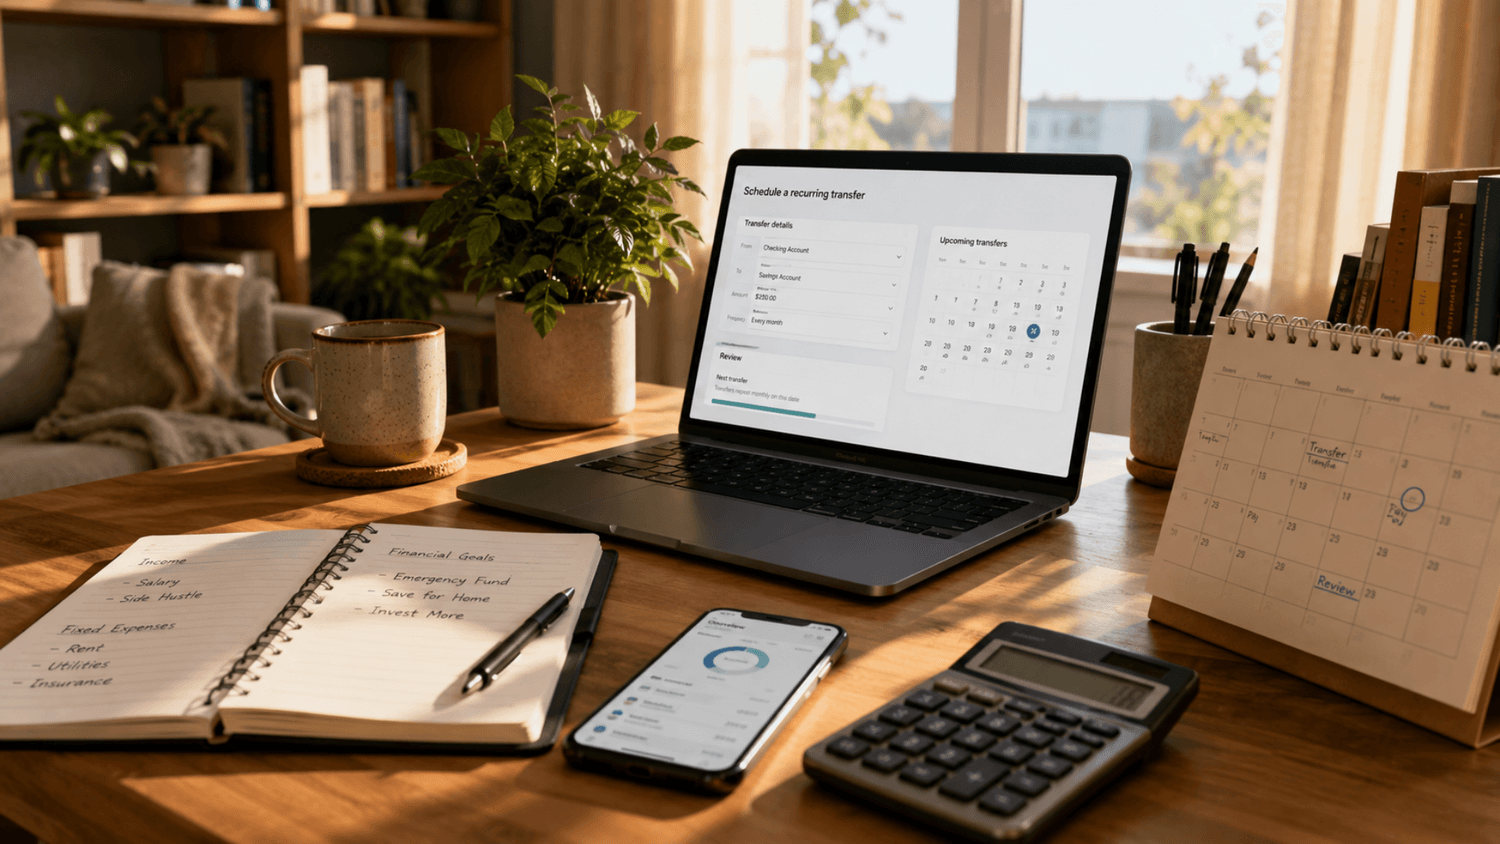
Schedule transfers soon after income arrives.
Money assigned immediately is less likely to disappear through unplanned spending.
Automation still requires review.
Check accounts regularly to prevent overdrafts, confirm that bills are correct, and adjust transfers when income or expenses change.
The best system combines automatic execution with human attention.
Create a Weekly and Monthly Financial Rhythm
Simple systems become easier when each task has a regular time.
A weekly review can take 15 to 20 minutes.
Use it to:
Check account balances.
Review recent transactions.
Confirm upcoming bills.
Correct unusual spending.
Make sure automatic transfers occurred.
A monthly review can go deeper:
Total the income received.
Compare planned and actual spending.
Measure savings and debt progress.
Review asset contributions.
Choose one adjustment for the next month.
This rhythm prevents small problems from remaining hidden until they become expensive.
It also gives you evidence of progress.
Account balances may grow slowly, but monthly records reveal direction.
You can see debt declining, reserves becoming stronger, and asset contributions accumulating.
That visible progress helps replace short-term excitement with long-term confidence.
💡 Turn Financial Intention Into a Working Routine
A repeatable review system can help you spend with greater awareness, prepare for setbacks, and keep building toward ownership.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Build a System Around Your Current Reality
Do not copy a system designed for someone with a completely different income, household, debt load, or stage of life.
Start with your actual situation.
If you have no emergency reserve, your first priority may be building a small cash buffer before increasing higher-risk investments.
If expensive consumer debt is draining your monthly income, reducing it may need greater attention.
If your basic foundation is stable, you may focus more heavily on retirement accounts and other long-term assets.
Your system should also be simple enough to maintain during a difficult week.
A complicated spreadsheet with dozens of categories is not helpful if you refuse to open it.
A basic notebook or budgeting tool that you review consistently may produce better results.
Use enough detail to make good decisions, but not so much that tracking becomes another form of avoidance.
Measure Progress With the Right Numbers
Income matters, but it does not tell the complete story.
A person can earn more and still remain financially fragile if spending rises at the same rate.
Another person may have a moderate income but steadily strengthen savings, reduce debt, and build assets.
Track numbers that show financial direction:
Emergency savings balance
High-interest debt balance
Monthly savings rate
Amount invested
Total recurring expenses
Net worth over time
Income produced by owned assets or business systems
Do not become discouraged by small early numbers.
Their purpose is to establish a baseline and show whether your actions are working.
Measure consistently—monthly or quarterly—rather than checking long-term investments obsessively.
Wealth-building decisions should be guided by your plan, not by daily emotion.
Increase the Gap Between Income and Spending
The foundation of the system is the gap between what comes in and what goes out.
You can strengthen that gap in two ways: spend more intentionally and increase income.
Expense control often creates the fastest immediate result.
Income growth may create greater long-term capacity.
Consider practical ways to improve income:
Develop a valuable skill.
Negotiate compensation using documented results.
Pursue better-paying opportunities.
Build a realistic side service.
Improve the profitability of an existing business.
Turn useful knowledge into an asset or product.
When income increases, decide in advance how much will support your future.
Without a plan, lifestyle costs can absorb every raise.
Even directing part of each increase toward savings, debt reduction, or investments can accelerate progress while leaving room to enjoy some of what you earned.
Make the Basics Your Financial Advantage
Many people will try a system for a few weeks.
Fewer will follow a reasonable plan for several years.
That difference matters.
You do not need to predict every market movement or discover a secret strategy.
You need a foundation that helps you keep more of what you earn, prepare for pressure, and acquire assets over time.
The basics become an advantage because most people underestimate them.
Track income.
Control spending.
Build assets.
Repeat.
Then improve the process gradually:
Raise your savings rate when possible.
Reduce unnecessary recurring costs.
Strengthen insurance and emergency protection.
Increase your financial knowledge.
Choose assets carefully.
Review progress without reacting emotionally.
Simple does not mean effortless.
It means clear.
💡 Start Building With the Numbers You Have Today
Financial progress begins when you stop waiting for the perfect strategy and start applying clear principles to your current reality.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Final Thought
People do not always avoid simple wealth systems because they are difficult to understand.
They often avoid them because simple systems make the next action obvious.
Once you know your income, spending, debt, savings, and assets, you can no longer pretend that vague intentions are enough.
That clarity is not a punishment.
It is an opportunity.
You do not have to repair everything at once.
Begin by looking at the numbers honestly.
Choose one useful action.
Repeat it until it becomes part of your normal financial life.
Wealth is not built by making money appear more complicated than it is.
It is built by practicing sound financial basics longer than most people are willing to continue.

Categories


Trending
Curious about Java Burn? Discover how this fat-burning coffee additive works, what ingredients it uses, and if it’s right for your daily routine.
Looking for real ways to make extra money in 2024? Here are 15 legitimate side hustles and online income ideas that actually work — no scams, no fluff.
Discover how to build real confidence using small, science-backed micro-habits. No fluff — just proven strategies that actually work.

About me

Hi there 👋 My name is Lisa Grove, I'm the maker of This Blog. One of my favorite things is travel, fun and sun :)
💡 Keep Exploring: Handpicked Reads for You
Discover proven strategies to attract leads using Facebook & Instagram — no ad budget needed.
Learn how to write subject lines and content that get clicks, opens, and responses.

Start your journey toward financial freedom with this simple, proven framework.
📬 Want Smart Marketing Tips in Your Inbox?
Join our free newsletter for weekly tips that help you grow faster and smarter.
© 2025 reebesthelp.com. All rights reserved.