

The “Money-In” Tracker Method: A Simple System for Understanding and Growing Your Income
Most people know how much their rent, mortgage, utilities, and subscriptions cost.
They can tell you when a bill is due and how much money is leaving their account.
But ask them exactly how much money came in during the last 30 days, and the answer is often less certain.
They may know their regular paycheck.
They may remember one or two additional payments.
But smaller sources of income are frequently overlooked: overtime, tips, commissions, refunds, freelance projects, marketplace sales, interest, bonuses, or occasional work.
That missing information matters.
You cannot make fully informed financial decisions when you only track one side of your money.
Expenses show what your current life costs.
Income shows what is supporting that life—and where your capacity to grow may exist.
The Money-In Tracker Method gives you a simple way to measure that side of the equation.
What Is the Money-In Tracker Method?
The Money-In Tracker Method is a record of every dollar you receive during a specific period.
It does not have to be complicated.
You can use a notebook, spreadsheet, printable template, or financial app.
The tool matters less than the habit.
Every time money comes in, record:
The date received
The amount
The source
The type of income
Whether it is recurring or irregular
Any taxes, fees, or expenses connected to it
The actual amount available after those deductions
This gives you more than a monthly total.
It helps you understand the structure of your income.
For example, two people might each receive $4,000 in one month.
However, their financial positions may be completely different.
One person may receive the full amount from a stable salary.
The other may earn it through several projects with unpredictable payment dates and significant business expenses.
The total is the same, but the planning needs are not.
A Money-In Tracker makes that difference visible.
💡 Know What Your Income Is Really Doing
Tracking what comes in gives you a clearer starting point for every financial decision.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Why Expense Tracking Is Only Half the Picture
Expense tracking is important.
You need to know where your money goes if you want to reduce waste, prepare for bills, and protect your cash flow.
But expense tracking has a natural limit.
You can cancel unused subscriptions.
You can compare insurance rates.
You can plan meals, reduce impulse purchases, and negotiate certain bills.
Those actions can create valuable breathing room.
Still, you cannot cut your way below the cost of your basic needs.
Housing, food, transportation, healthcare, utilities, insurance, and taxes will continue to exist.
At some point, the stronger financial question becomes:
How can I improve what is coming in?
That is where an income tracker changes your perspective.
Instead of seeing money only as something you must protect from expenses, you begin examining it as something you can understand, strengthen, and diversify.
This does not mean chasing every possible side hustle.
It means using actual numbers to determine what deserves your attention.
Awareness Creates Better Financial Action
Financial improvement rarely begins with a dramatic move.
It usually begins with seeing something clearly enough to act on it.
Suppose you begin tracking every dollar and discover that you earned an additional $280 last month through overtime.
That may show you that occasional extra shifts can help fund a specific goal.
Perhaps you earned $175 selling unused household items.
That income may not continue forever, but it could help you build an emergency cushion without affecting your regular budget.
Maybe a freelance service brought in $600, but payment-processing fees, supplies, transportation, and taxes reduced the usable amount to $390.
Without tracking the details, you might overestimate how profitable that work really is.
Each example gives you information you can use.
Tracking helps you identify:
Which income sources are dependable
Which sources fluctuate
Which activities produce the best return
Which payments arrive late
Which earnings require tax planning
Which sources could potentially grow
Which activities consume too much time for too little return
Awareness alone does not increase income.
But awareness shows you where your next useful action may be.
Gross Income and Usable Income Are Not the Same
One of the biggest mistakes people make is recording only the amount received.
If a client pays you $500, it is tempting to treat the entire $500 as income you can spend.
But if you paid $75 for materials, $25 in platform fees, and need to reserve $100 for taxes, your usable amount is closer to $300.
Your tracker should make this visible.
A simple entry could include:
Gross payment: $500
Fees and direct costs: $100
Tax reserve: $100
Usable income: $300
This matters most when income comes from self-employment, contract work, online sales, commissions, or a small business.
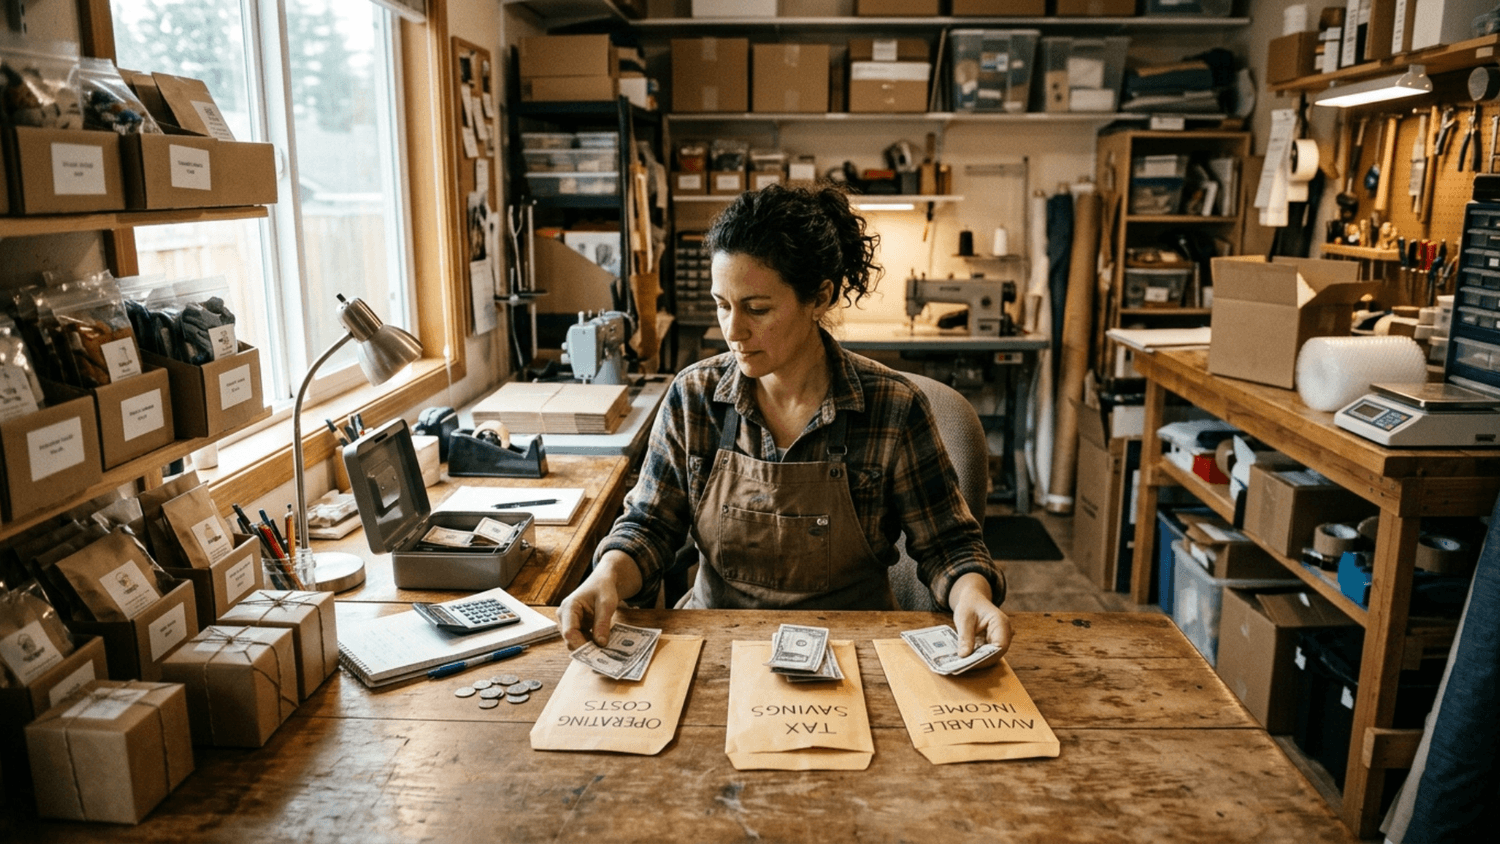
When gross income and usable income are mixed together, it becomes easy to overspend, underfund taxes, or assume an activity is more profitable than it is.
The Money-In Tracker Method keeps the numbers honest.
💡 Separate Revenue From Money You Can Use
Clear income records help you plan for taxes, fees, business costs, and personal goals before the money disappears.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
How to Build Your Money-In Tracker
You do not need a complicated financial dashboard.
Start with a few clear columns that you can maintain consistently.
1. Date Received
Record the day the money actually reached you.
If someone promises to pay you on Friday but the payment arrives the following Tuesday, Tuesday is the date that belongs in your tracker.
This gives you an accurate picture of cash flow.
2. Income Source
Name where the money came from.
Examples include:
Primary job
Overtime
Freelance client
Rental payment
Product sale
Affiliate commission
Interest
Refund
Bonus
Marketplace sale
Consistent labels make your records easier to review.
3. Income Category
Group similar sources together.
Useful categories might include earned income, business income, investment income, rental income, refunds, reimbursements, or one-time income.
This helps you see whether your earnings depend heavily on one category.
4. Gross Amount
Record the full amount received before deductions.
5. Costs and Deductions
Include platform fees, transaction charges, supplies, transportation, commissions paid, and other direct costs.
6. Tax Reserve
If taxes were not withheld, record the amount you intend to set aside.
The appropriate amount depends on your circumstances, so consider qualified tax guidance when necessary.
7. Net or Usable Amount
This is the amount remaining after direct costs and planned reserves.
8. Recurring or Irregular
Mark whether the income is expected to return on a predictable schedule.
This one detail can improve your planning.
Recurring income may support regular obligations, while irregular income may be better directed toward savings, debt reduction, repairs, or other flexible goals.
Create a Weekly Tracking Routine
Waiting until the end of the month makes the process harder than necessary.
Small payments can be forgotten, fees may be overlooked, and details become more difficult to reconstruct.
A weekly routine is more reliable.
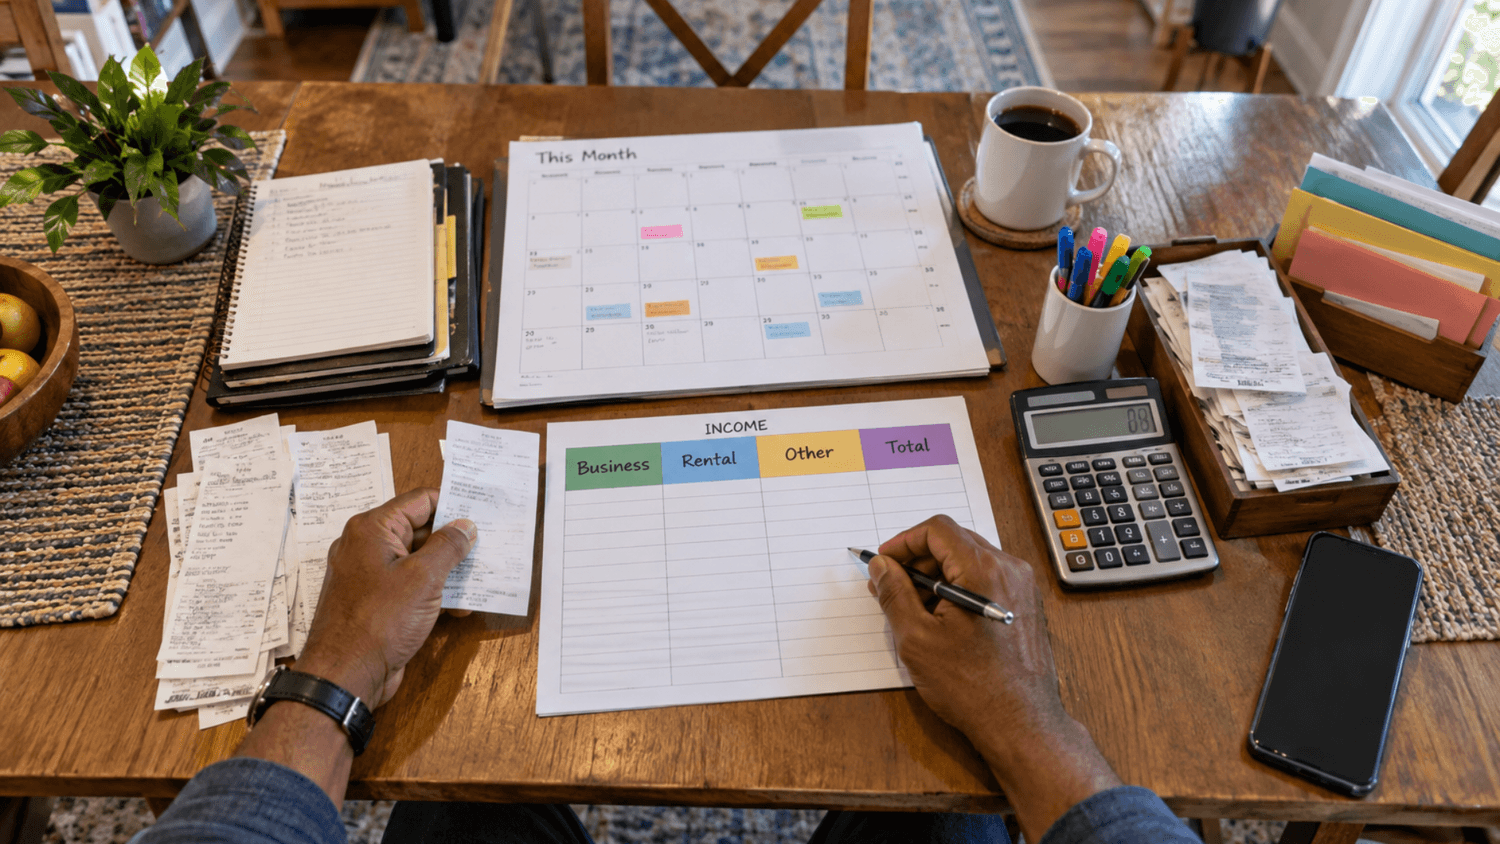
Choose one day and spend 10 to 15 minutes updating the tracker.
During that review:
1. Check your bank and payment accounts.
2. Record all new income.
3. Confirm fees and direct expenses.
4. Set aside money for taxes when applicable.
5. Mark unpaid or delayed payments.
6. Review your month-to-date total.
The routine should be simple enough to repeat even during a busy week.
Consistency matters more than perfection.
If you miss an entry, add it when you find it.
The goal is to improve visibility—not create another source of pressure.
Review the Numbers at the End of Each Month
Your tracker becomes more valuable when you stop merely recording and start reviewing.
At the end of the month, calculate:
Total gross income
Total income-related costs
Total reserved for taxes
Total usable income
Income by source
Recurring income
Irregular income
Unpaid money still expected
Then compare the results with the previous month.
Do not judge one month in isolation, especially if your income fluctuates.
Look for patterns across three, six, or twelve months.
You might notice that:
Certain months consistently produce more overtime.
One client pays reliably while another regularly delays payment.
A small income stream is growing steadily.
Seasonal work creates predictable peaks and slow periods.
One service generates more usable income with fewer hours.
Additional earnings keep disappearing into unplanned spending.
These patterns help you prepare instead of react.
Turn Income Data Into Decisions
The tracker is not the final goal.
Better decisions are the goal.
Once you understand your income patterns, ask practical questions.
Which Source Deserves More Attention?
A modest income source may have room to grow.
If a service consistently produces good returns and fits your available time, you might promote it more deliberately or improve how you deliver it.
Which Source Is Less Valuable Than It Appears?
A payment can look attractive until you include travel, supplies, fees, taxes, and time.
Your records may show that the work needs a higher price, lower costs, or a different process.
Is Your Income Too Dependent on One Source?
A dependable primary income is valuable.
However, understanding your level of dependence allows you to prepare for disruptions.
Diversification does not require building five businesses.
It could mean strengthening your skills, maintaining professional relationships, developing one supplemental service, or creating a larger emergency reserve.
Are Irregular Earnings Being Used Intentionally?
When unexpected money arrives, it can disappear quickly because it was never assigned a purpose.
Your tracker can help you create a rule for irregular income.
You might direct a percentage toward:
Emergency savings
High-interest debt
Taxes
Retirement
Home or vehicle repairs
Business improvements
A planned personal purchase
The percentage matters less than making the decision before the money is absorbed into everyday spending.
💡 Give Every New Dollar a Clear Purpose
Use your income records to decide what should support today, what should protect tomorrow, and what can create future growth.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Avoid These Common Tracking Mistakes
A tracker is useful only when the information is accurate enough to guide you.
Tracking Only Your Main Paycheck
Small payments count. Individually, they may seem unimportant.
Together, they can reveal meaningful earning patterns.
Counting Transfers as Income
Moving $300 from savings to checking does not create $300 of new income.
It only changes where the money is stored.
Credit-card cash advances and borrowed money are not income either.
They create debt that must be repaid.
Counting Promised Money Too Soon
An invoice is not usable income until it is paid.
Track pending payments separately from money received.
Ignoring Refunds and Reimbursements
A refund may increase your available cash, but it usually is not newly earned money.
Label it accurately so your income totals are not distorted.
Forgetting Fees and Taxes
Gross payments can create false confidence.
Record the amount that will actually remain available.
Building a System You Will Not Maintain
A complicated tracker filled with formulas and categories may look impressive, but it provides little value if you stop using it.
Choose the simplest system that answers your important questions.
Use a Three-Month View Before Making Major Changes
One month can be unusual.
You may receive a bonus, complete a large project, miss work, or experience a seasonal slowdown.
A three-month view gives you a more dependable starting point.
Add your usable income for the last three months and divide the total by three.
This produces a basic monthly average.
If your income fluctuates significantly, plan regular expenses around a more conservative number rather than your best month.
If your income fluctuates significantly, plan regular expenses around a more conservative number rather than your best month.
If your income fluctuates significantly, plan regular expenses around a more conservative number rather than your best month.
The longer view can reveal seasonal patterns and improve major decisions involving housing, debt, business investments, or recurring commitments.
Set One Income-Focused Goal at a Time
After reviewing your tracker, select one realistic goal.
You might decide to:
Increase usable monthly income by $200
Collect invoices within 14 days
Reduce transaction fees
Raise the price of an underpriced service
Request one additional shift each month
Save half of all irregular income
Build one month of income reserves
Replace an unprofitable activity
Tie the goal to something your records revealed.
“Make more money” is too broad.
“Increase net freelance income by $200 per month without adding more than five working hours” gives you a target you can measure.
Review the goal monthly.
If the strategy works, continue or expand it.
If it does not, adjust it based on evidence.
💡 Build Growth From Numbers, Not Guesswork
A measurable income goal helps you focus your time, protect your resources, and recognize real progress.
👉 Build smarter financial habits today:
Small financial shifts create long-term freedom.
Final Thought
The Money-In Tracker Method is not about obsessing over every dollar.
It is about understanding what your effort is producing.
When you record every source of income, separate gross payments from usable money, and review the patterns regularly, your finances become easier to evaluate.
You can see what is dependable.
You can identify what needs improvement.
You can prepare for irregular months and direct additional income toward goals that matter.
Start with the money that comes in today.
Record the source, the amount, the costs, and what remains.
Then continue.
Track.
Review.
Improve.
Repeat.
Financial growth becomes more practical when you stop guessing and start working with clear information.

Categories


Trending
Curious about Java Burn? Discover how this fat-burning coffee additive works, what ingredients it uses, and if it’s right for your daily routine.
Looking for real ways to make extra money in 2024? Here are 15 legitimate side hustles and online income ideas that actually work — no scams, no fluff.
Discover how to build real confidence using small, science-backed micro-habits. No fluff — just proven strategies that actually work.

About me

Hi there 👋 My name is Lisa Grove, I'm the maker of This Blog. One of my favorite things is travel, fun and sun :)
💡 Keep Exploring: Handpicked Reads for You
Discover proven strategies to attract leads using Facebook & Instagram — no ad budget needed.
Learn how to write subject lines and content that get clicks, opens, and responses.

Start your journey toward financial freedom with this simple, proven framework.
📬 Want Smart Marketing Tips in Your Inbox?
Join our free newsletter for weekly tips that help you grow faster and smarter.
© 2025 reebesthelp.com. All rights reserved.